October is Fraud and Financial Awareness Month. For this reason, I think it is a great time to share with you some information about elder abuse and financial scams. As you know, our firm assists a lot of older or vulnerable adults and we enjoy being able to help protect individuals and families from harm. Over the next few weeks, I will introduce the topic of elder abuse and discuss who is at risk. I will also explain why older adults are often a target of abuse and the various types of scams used. Finally, I talk about what to watch for and some ideas on how you can protect those around you.
How common is elder abuse in America?
There are higher rates of elder abuse in the United States than in most countries. The National Council on Aging reported that about 10% of older Americans have experienced some form of elder abuse, with many of the victims exploited more than once. Unfortunately, a high percentage of these crimes go unreported. Therefore it is estimated that only 1 in 24 instances of abuse are actually reported. Understandably, these are alarming statistics!
[A] single or repeated act, or lack of appropriate action, occurring within any relationship where there is an expectation of trust, which causes harm or distress to an older person. This type of violence constitutes a violation of human rights and includes physical, sexual, psychological, and emotional abuse; financial and material abuse; abandonment; neglect; and serious loss of dignity and respect.
Who is at risk for elder abuse?
Many older adults experience medical conditions that can lead to a reliance on a larger network of people to assist with day-to-day activities. This leaves the elder exposed to more opportunities for elder abuse. Unfortunately, this is all too common. Many of us have heard stories about friends and family members being victims. Below is a list of those who are at higher risk for elder abuse:
Individuals who live with mental or physical disabilities.
Widowed women.
An elder who lives with someone who is financially dependent on, emotionally disconnected with or resentful of the vulnerable adult.
Socially isolated individuals.
An elder who lacks familial connections or financial means.
Elders who live in institutions or long-term care facilities.
Do you know an aging person who has been exploited or neglected?
Can you think of an instance where an elderly person in your network has been taken advantage of? Is someone in your family receiving phone calls demanding them to pay back taxes? Has a relative suddenly started dating a prince overseas?
These situations are just a fraction of the examples of elder abuse. The rest of the posts this month will go over the most common ways elders are financially exploited, how to spot tricky behavior from others, and what to do if you or someone you care about is a victim.
We’ve been talking about Medicare for a few weeks now, but we haven’t gotten to the how-tos yet. That’s about to change. Today we dig into how you actually enroll in Medicare.
To sign up for Part A, go to the Social Security Administration’s Medicare portal here. It will be helpful to set up an account for when you come back to sign up for Part B or when you are ready to begin receiving retirement benefits.
If you are signing up for Parts A and B, the process is the same. You’ll sign up through the Social Security Administration’s website. Remember that if you enroll for Part B, your premiums will either be deducted from your Social Security retirement payment or you will receive a bill. The 2021 Part B premium is $148.50 for most people.
If you are looking for a Medicare Advantage plan, Part D, or a Supplement (Medigap) plan, you will want to compare plan options using a plan comparison service. There are insurance brokers like Kendall Chanley and Harry Perret here in town who can help you compare options and narrow things down. Once done, they will get you signed up. These services are free to you and it’s nice to have one agent who can help you each year.
If you prefer to do things yourself or just want to do some exploring, Medicare.gov will allow you to find plans in your area and narrow them down based on what you are looking for and price ranges. I recommend filtering plans by the star ratings (four or above) and then whether you are looking for dental, vision, and prescription medicine access.
Once you make it through your first enrollment period at age 65 (ideally), you’ll be eligible for open enrollment each year from October 15th through December 7th. You may also have options to select coverage during a special enrollment period if you lose other coverage.
Applying for Medicare isn’t nearly as scary as it sounds, but it does require advanced planning and research. You don’t want any deadlines sneaking up on you! Personally, I love using reminders on my calendar well in advance of any deadlines that I have. Maybe one to begin research, one to call an expert, one to compare plans, one to sign up….all before your birthday or November.
What’s your plan for Medicare enrollment? Head to our Facebook page to share your plans in the comments!
I don’t know about you, but I don’t plan to retire at 65. I mean, that’s only 25 years away. And I like my job. Maybe that’s you.
Even still, don’t put off signing up for Medicare when you turn 65. Here’s Why.
Mistake #1: Waiting until after you retire to sign up for Part A.
Why it’s a mistake: Medicare is basically free money. You paid for it with your taxes for the past forty-some years…but still.
Ultimately here’s the deal–you CAN wait. But since it’s no skin off your back, wouldn’t you rather set it and forget it? Think about that time you set up automatic payments into your savings account or 401k. You may not have missed the money, but when you got your tax forms, you saw the benefit of making a small change. It’s the same here. Signing up for Part A is easy, and makes the process of signing up for Part B or a Medicare Advantage plan much easier.
Mistake #2: Staying on private health insurance coverage instead of signing up for Part B, without doing further research.
Why it’s a mistake: The plan you are currently on may not provide enough coverage.
If you plan to stay on your current coverage instead of signing up for Part B as soon as you turn 65, you want to make sure that your health plan provides appropriate coverage. We’re talking about a qualified group health plan (as defined by the IRS). If you’ve ever had to provide proof of “creditable coverage” for plan enrollment, this is similar. Otherwise, you will pay a penalty when you sign up for Part B coverage. This penalty is paid with each premium payment and never goes away. The longer you are eligible for Part B without signing up, the more the penalty costs. Do your future self a favor and get HR to confirm (in writing) that your current coverage meets the requirements.
Mistake #3: Assuming that your current insurance plan will continue to be available after you become eligible for Medicare
Why it’s a mistake: Believe it or not, some insurance plans and employers will not cover you (or your spouse) if there is other coverage available elsewhere. That includes Medicare. Medicare enrollment begins three months before you turn 65 and lasts three months after. Start looking at your options early to make sure you don’t get left without insurance unexpectedly.
Whatever you decide about retirement, make sure that you have the information you need to make good, informed decisions.
Next week we’ll be getting into the nitty-gritty of how to actually sign up for Medicare. Make sure to follow us on Facebook or Instagram to see when the blog gets posted!
Healthcare in America is…..complicated. Medicare ensures that most people 65 and older have access to basic care for hospitalization and doctor’s care.
But what else does it include? That’s a great question….because it all depends on what you sign up for. Some of it will depend on the specific plan you sign up for but all plans include core services. If we talk about Part A or Part B coverage, a Medicare Advantage plan (Part C) automatically includes these same services. If you didn’t catch our Medicare 101 post last week, go catch up here.
I had the good fortune to go through a training hosted by the State Health Insurance Program a few years ago that really opened my eyes to how Medicare coverage works. It was one of my first steps into the realm of elder law.
Since then, I’ve helped clients who are on Medicare and helped my parents navigate the process too when my Dad turned 65. I wanted to share some of my favorite free resources to find out information about Medicare. Depending on whether you like to keep things old school, or want things as paperless as possible- there’s an option for everyone!
By mail- When you sign up for Medicare, you will get a Medicare and You handbook that is useful for helping you figure out what is included in Parts A and B. It is easy to read and understand exactly what your coverage includes.
By phone- As I mentioned above, the State Health Insurance Program (SHIP) is an awesome program that helps Tennesseans find the right health care plans for them. You can reach them at 1-877-801-0044 or, in the before times, at local health fairs. Just remember that they are staffed by volunteers and might take some time to call you back. If you’d like to become a volunteer, they would love to have you!
Online: Yes, I know that government websites don’t have the best reputation for having easily accessible information. But trust me….Medicare.gov is different. Whether you just want to learn about Medicare, compare plan options, or look for a new doctor, this website makes it simple to find what you’re looking for.
In your pocket- The Medicare “What’s Covered” App is available for Apple and Android user. You can open your phone to find out if a service or treatment your doctor recommends is covered and how much it is likely to cost out of your pocket. I’m pretty jealous that my insurance company doesn’t offer this.
All of these options now have online availability (check out those lovely blue links). Regardless of how you prefer to absorb information, I hope you’ll find one resource that is your favorite. We will be polling our social media readers on Facebook and Instagram this month to see what their favorite Medicare resources are…..we hope we’ll see you there!
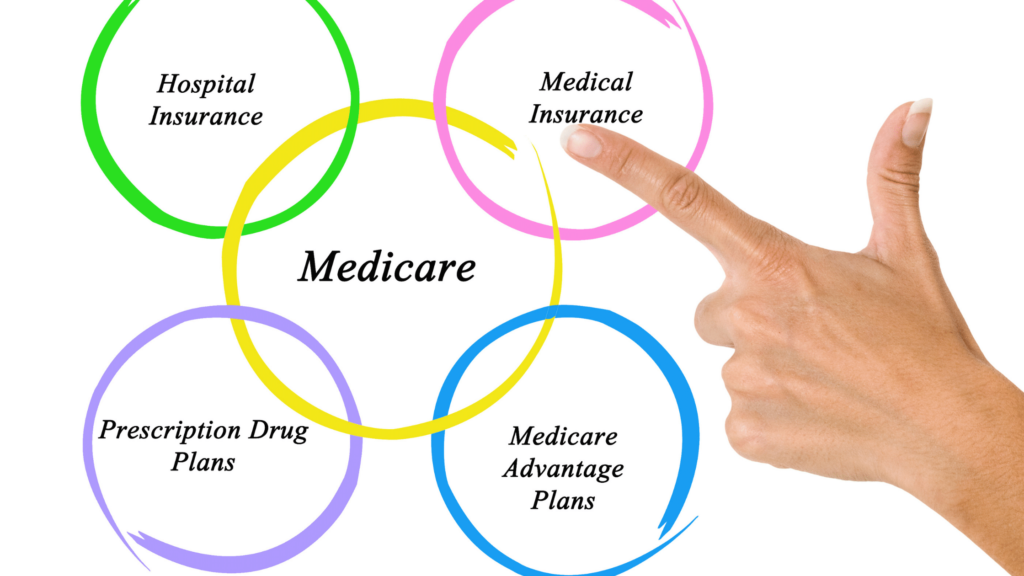
As if choosing health insurance under an employer’s plan wasn’t difficult enough, figuring out which type of Medicare plan is best for you is even more confusing. I call Medicare an alphabet because there are 4 parts- A, B, C, and D. Oh, and you might want to consider a supplement too!
Don’t worry. With a little time and some guidance, you can master the Medicare alphabet just like you mastered your ABCs!
First, let’s go through the four types and what they cover.
Part A only covers emergency care, such as if you need to stay at the hospital.
Part B covers regular care like doctors visits, bloodwork, and any other testing or treatment that your doctor recommends.
Part C is often referred to as an “Advantage Plan”. It is administered by private insurance companies, just like an employer’s plan. It includes Part A and B coverage and may include other benefits as well, such as dental, vision, and prescription drugs.
Part D covers prescription drugs. That’s it.
When you approach age 65, ask yourself what your current health needs are, what family history might impact future healthcare needs, and what type of coverage you are used to receiving. Then look at your budget.
Part A is free for those who are eligible through their tax contributions. In 2021, most individuals will pay $148.50 per month for Part B, although the amount can be higher depending on your income.
If you anticipate that you will need something more than just emergency and regular doctor’s visits, there is another alternative. Consider a Part C “Advantage” plan or a Medicare Supplement (or “Medigap” plan), instead. This plan will provide coverage for those things that Parts A and B don’t, like such as prescription medications, dental, or vision care. Keep in mind that you still pay co-pays and deductibles on Medicare, so you will want to look at those amounts and not just your premium when considering your budget.
When thinking about the Medicare alphabet, I have a little way to help me remember what each part covers:
A is for an Accident that lands you in the hospital
B is for Bloodwork they do at the doctor’s office
C is for Comprehensive coverage you can get with an Advantage plan
D is for Drugs (They made that one easy!)
Now you know your ABCs….next week I hope you’ll join us when I share my favorite FREE resources to learn about Medicare before you sign up.
Choosing a legal guardian who can raise your kids if you are unexpectedly incapacitated or pass away can be a daunting and difficult challenge. There are many things to take into account such as parenting styles and the potential guardian’s ability to love and take care of your children.
These are just some of the questions we believe every parent should answer before naming a guardian.
Where will your children live? Many parents desire to keep their children in a familiar environment if something unfortunate happens. It’s not unusual for parents to put instructions in their estate plans regarding the cities or states they want their kids to be raised in if mom or dad passes away. If the geographical location of where your kids will be placed is important to you, be sure to make this known to your Davidson County will attorney when creating your plan.
Are your children familiar with the potential guardian? It is important that your children are comfortable with the guardian you are about to choose for them. If you are selecting a guardian that lives far away, you may want to consider ways to begin cultivating a relationship between your children and the potential guardian before it’s needed. Naming a temporary guardian is also important in such situations. This will ideally be a person that lives close by and can help ease the transition to your kids relocating to their permanent guardian’s home.
Is your potential guardian prepared to care for your children? There are many factors that could fall under this category, but it is important to make sure that your guardian is emotionally, physically, and financially prepared to care for your child/ren. For example, you may want a grandparent to become guardian, but their age and their own financial and/or medical needs may make serving in this role difficult for them. Don’t forget to take their point of view into account when making your selection.
Do any of your children need special care? If you have a child with a mental or physical disability, it could take special knowledge and resources to care for your child. It is important to make sure that the named guardian would not be overwhelmed by this responsibility and that they are prepared to care for your child in whatever way that your child may need.
Have you discussed this choice with your potential guardian? It is very important that you ask your potential guardian if this is a responsibility that they can take on. You will also want to talk about your desired path for raising your child/ren to make sure that you are in agreement and that your wishes will be followed.
As parents, you spend a lot of time planning the best future for your children. Make sure that your planning includes naming a legal guardian should you become unexpectedly incapacitated or pass away. You should be the one making that decision – not the courts. Schedule a call with our Davidson County will law firm today, so you can have the peace of mind knowing your children will be cared for by the person you want, in the way you want if anything happens to you.
From a legal standpoint, moms and dads don’t have a lot of rights after you turn eighteen. But we often rely on our parents more than we realize, something I was jerked into remembering during my junior year of college when I was rushed to the emergency room and soon told that the surgical team was ready for me. Ummmm….can’t I call my mom first???!!!
Fortunately my situation worked out, but as a lawyer, I can’t help thinking about what if I had not been awake to call my parents. What if I needed more extreme medical treatment and couldn’t tell the doctors what I wanted?
This is where you can learn from my mistakes. Get your legal shit together before you head off to college. Or after. But as soon as you can. I will even help you get everything completed by video call.
As a bona fide adult, you need a minimum of three documents in case of an emergency:
Healthcare Power of Attorney– This document allows you to appoint someone you trust to be your health care agent if you ever become incapacitated and unable to speak for yourself.
Financial Power of Attorney– A financial power of attorney allows you to give someone else permission to access bank accounts and act financially on your behalf if an emergency occurs. That means paying bills, completing financial aid or loan applications, dealing with insurance companies, and other ways that, well, adulting sucks. You’ll need to choose whether you want this to become effective immediately or only when you are unable to handle your own business.
Signed HIPAA Form– Now that your parents don’t have access to your medical records, you might want to consider authorizing someone to see them. Often family is a good go-to for all things medical (see: hereditary conditions) but you can name anyone-and everyone- you’d like. Mom, Dad, Brother, Best Friend, Fifth Grade Teacher? If you love them enough to share your blood panel results, then a HIPAA waiver is no biggie.
If you wanna get fancy, you can also sign a FERPA waiver to let your trusted adult have access to your educational record. It’s the grown-up version of the school sending home your report card to show how smart you are. 🤓
These are your documents, so you can name any adult you want to act in case you can’t (or don’t want to). In most cases that’s a parent, but let’s be real. Not all parents are created equal. Sometimes your “trusted adult” is your aunt, your neighbor, or your cousin. Whoever you name, it should be someone you trust with your life and your 💵 bank account.
When you’re ready to start getting your adult shit together, feel free to book a call with us or shoot us a text. The cost for all of these documents together is $500 through our office, and I bet mom and/or dad would even be willing to foot the bill if you show them how responsible you’re being!
In life, there are jobs we seek out and others that are given to us. Being named an Executor (or Personal Representative) of an estate is one of the most important jobs one can be asked to hold by another person. It means there is someone who trusts you fully and believes that you will manage their final wishes properly and without conflict.
That’s not to say the job is easy. Again, you were likely appointed to the role of Executor because your loved one felt you could handle any stress or difficult responsibilities that come with the job.
The good news, however, is that there are ways to prepare in advance so that your life as an Executor is easier when the time comes. Here are some suggestions a Middle Tennessee will lawyer would have you consider:
Have the hard conversations now. Meet with the person who is naming you as an executor of their estate and ask them to describe exactly how they wish their estate to be administered. Take notes and make sure you get all the details. Knowing the “why” behind the decisions in the will can help you navigate “gray area” choices if they arise.
Be organized. The job of an Executor consists of lots of paperwork, bureaucracy, and time maintaining the estate as it goes through the probate process. Set up a filing system, spreadsheets, and bins, so the Executor’s job does not infringe on your everyday life.
Get a lawyer. No matter the size of the estate, it is prudent for all involved parties to have a lawyer. At the minimum, have a consultation with an attorney to make sure there is not something you have overlooked. People often think they can do everything themselves only to be caught at the end by taxes or administrative issues.
Move quickly once the person passes away. Grief makes people act in unexpected ways, so it is imperative that after the person dies, you move quickly to locate the original final will and file the necessary paperwork with the courts to be recognized as the Executor. At this time, order up to 8-10 copies of the death certificate to save yourself time later. Another uncomfortable thing you will need to do is to secure the assets. All too often, grieving loved ones will go to the home and begin to take items they believe they should have. You will have to be the one who stops this.
Be upfront with the heirs of the estate. Make sure they all get a clear understanding of how estate administration works. The process is a slow one, which frequently frustrates family members who are grieving. By giving them an explanation or better yet, having a lawyer do it, they will hopefully have patience with you and avoid conflicts.
Know there will be conflicts. Grieving is an individual process, and you will take the brunt of most of that emotion. If money is involved in the administration, the speed at which money is inherited can be infuriating. Heirs becoming angry with you is even more of a probability if any perceived omissions or secret bombshells are in the will. Hopefully, if that is the case, you knew ahead of time and were prepared.
Heirloom distribution needs to be deliberate. Once the significant assets and personal items are named in the will, the hard part starts. Deciding who receives the personal items in the home can cause the most conflicts. There is no explanation for the small household items that might have importance to many family members. A sweatshirt, a picture frame, or a dish can hold deep memories that you might be unaware of. Creating an equitable system for if multiple people want an item will ensure this process is done deliberately.
These are only a few ways you can help yourself if you have been named an Executor. If you find yourself struggling with your duties or you have questions and need some advice, we are here to help. To have an appointment with our Middle Tennessee will lawyer, April, schedule an initial call with us today!
In the majority of cases, it’s a biological parent (or parents) who will apply to become their child’s legal conservator when they turn 18. But even parents will ask us if they are able to appoint an “alternate conservator” or someone else who can help with all required responsibilities and duties. Most commonly, we are asked by parents of individuals with special needs if they can appoint one of their other adult children, a stepparent, a sibling, a grandparent, or other relative to serve as co-conservator who could have the same legal rights as the main conservator.
Legally speaking, having a co-conservator is absolutely possible, and it’s something we often consider to help lighten the load. However, the parent or main conservator cannot appoint this person themselves. Instead, the candidate will need to go through a formal legal process with the Tennessee courts where they will petition to serve as a co-conservator. During this process, the court will need to verify that the person is indeed capable of serving in this capacity, and from there, a judge will ultimately approve or deny the request.
When we meet with families to start the process of filing for a conservator over a young adult with special needs, we will typically ask up front if the main candidate for conservatorship wants someone else to serve in a co-conservator role. In general, it’s easier and less expensive to take care of everything all at one time. The bottom line is that every family is different, and it’s important to work with an attorney who will help you create an individualized plan that actually works over the long haul.
Here at the Graceful Aging Legal Services, we want parents and caregivers to feel as secure and supported in their roles as possible, as that ultimately results in the best care for the person with special needs. If you have questions about how to create a Special Needs Plan that takes into account the unique dynamics or challenges in your family, please feel free to contact us at (615) 846–6201 to schedule an appointment.
Have you ever thought about what you want to happen to your “digital assets,” including your Facebook page, after you pass away?
This is a question that Big Tech giants have spent the past few years grappling with as more and more of our lives are lived online. As such, companies like Facebook have started developing solutions to help account holders more easily “pass on” their digital real estate to loved ones and friends following their death. “Legacy Contacts” is one such feature that permits this to happen on the platform.
Until the creation of the Legacy Contacts, loved ones of the deceased only had two choices to manage an existing Facebook Account:
Leave it a public wall (that no one had “behind the scenes” access to) where people could continue to post messages; or,
Request that the page be “memorialized,” which rendered the profile invisible and unsearchable to those who were not already connected with the account.
Now with the Legacy Contact feature, Facebook account owners can name who they want to manage their profile in their absence. This “heir” would immediately have access to friend requests, pictures, and the management of content on the profile page.
Or, for those who want their Facebook account to remain private, the Legacy Contact feature also gives users the option to request a full deletion of their account after death.
Type in a friend’s name in Choose a friend and click Add.
To let your friend know they’re now your legacy contact, click Send.
To change or remove a legacy contact, follow steps 1–2 above, then click Remove. From there, you can add a new legacy contact if you’d like.
If your account is memorialized, your legacy contact will be notified. Learn more about what a legacy contact can do. Note: You must be 18 or older to select a legacy contact.
Utilizing Legacy Contacts is an easy and straightforward way to let Facebook know how you want your private social media information to be handled after your passing. If you have any additional questions about how to include your digital assets as part of your estate plan, please contact our office to schedule an appointment.