Many people think that if they are married, their spouse will automatically inherit everything when they pass and so they don’t need a will. While there are some situations where a spouse does inherit everything, it is not the default under Tennessee law. In Tennessee, if you are married and have children, your spouse will share your probate estate with your children. I call this the S.A.K.S. method (Spouse and Kids Share). In other words, your spouse does not inherit everything automatically.
To clarify:
If you die without a will, Tennessee law dictates that the spouse and children split the estate.
However, I believe that everyone should create their own plan for distributing their assets after death, even if the state has an understandable default on how to do this. Here’s why:
Having a Will can make it easier for your family to go through probate.
Having a Last Will and Testament can be an important way to reduce any burden on your family after your death. In your Will, you decide not only who will inherit your estate but also key decisions like who will serve as Personal Representative (also known as the Executor) and whether you want to require or waive documents that are required by statutes. Having a Will is your chance to have a say in the probate of your estate before you die. The process can be much less complicated for your beneficiaries as well because you may decide to be even more specific about some of the more difficult decisions that need to be made.
It is much easier on your family if you have an estate plan in place. A last will and testament will provide instructions on how to designate and divide assets between family members and friends. If you die intestate (without a will), then the state’s inheritance laws will determine who gets what.
Preparing an estate plan will cover situations that may arise after your passing
Have you considered what might happen if your spouse remarries? Are you aware that a future spouse can take an interest in a portion of your estate? Would you want part of your assets to go to a new spouse or to any children that they may have with that spouse? Do you have family or children that should benefit instead? There are many other factors to consider, but it’s important to discuss these things with your attorney when you create your estate plan.
A Will provides security for your spouse
If you are more concerned about your spouse inheriting from you than your children, you can plan for that too! The general rule in Tennessee is that the spouse would get no less than a third of the estate.
For example, if you are splitting the estate with two or more children, the spouse would get a third. If there is only one child, the spouse would get half.
What if you want to provide more? With a Will, you can designate that your spouse gets everything or only leave certain things to your children. Many spouses write “I love you” wills, where they inherit first from each other, and then their children only inherit when the second parent dies.
Use a Will to protect spousal inheritance from changes in family dynamics
Another consideration in making a Will is your family dynamic. Do you have children from different relationships throughout your life? Do you have concerns about how your children from those relationships will get along with your current spouse when it comes to your estate? It is important to consider how you want inheritances to be split. Your Will can dictate how your assets will be handled! You can also designate your preference for the guardian of any minor children in the event that both you and the other parent die.
Additionally, a Will provides provisions such as the appropriate age at which your children should take over responsibility for managing any inheritance. One primary concern many parents have is whether young adults will be mature enough to make sound judgments concerning any money they inherit. Your Will can establish a certain age at which young adults gain control of their inheritance, to ensure that it isn’t squandered when you would prefer it be used towards education or sound investments.
In short, your Last Will and Testament should be drafted so that your wishes regarding your family are honored.
A Will can safeguard your beneficiaries if they become disabled
Are any of your assets expected to go to a loved one who has a chronic medical condition? If so, you’ll want to consider that an inheritance could disqualify them from any means-tested government benefits that they may receive or be entitled to, which could be devastating if they are counting on that benefit. The most common examples of this are Supplemental Security Income (SSI) and TennCare (Medicaid). You’ll want to have a contingency plan in your estate plan to make sure that their benefits are secure and not at risk of being cut off due to an inheritance. You don’t want their government assistance to decrease just because you died! You definitely need a plan for that. Make sure to work with a qualified estate planning attorney so you can refrain from making errors with your family’s benefits.
If you want control over who can access your digital assets, you must make a Will
Many digital assets are governed by terms and conditions which are unlikely to specify who will take over your accounts when you die. Some providers, such as Facebook, permit you to designate someone as a “legacy contact.” However, not all companies are robust enough to provide this type of service. A Will protects your digital assets from falling into the wrong hands or being lost in digital space with no one able to claim them. Check out our blog post about how to create or change your Facebook “legacy contact” here.
In conclusion
These are just a few of the things that you’ll want to consider when making an estate plan. I want to encourage you to have a long discussion with your spouse about how your assets should be split when one of you dies. There shouldn’t be any surprises! I cannot stress the importance of knowing each other’s values and putting them in writing. It is crucial to have the outcome you desire. A failure to plan can end up in expensive court litigation. This is why we encourage everyone to speak with an experienced estate planning attorney about how they and their spouse can protect each other through proactive planning.
Are you ready to make your Will? Schedule a free initial call and make your plan with the Team at GALS!
Many people have sufficient income to maintain a regular lifestyle but are unable to afford the high cost of long-term care. With the average cost of long-term care around $7,000.00 a month, it is incredibly difficult for most families to afford it, even more so after retirement. That’s why it’s a good idea to plan for qualifying for TennCare, also known as Medicaid.
Evaluate and restructure your assets to qualify for TennCare
It’s worthwhile to know how to qualify for TennCare
As we discussed in our blog last week, there are certain criteria you need to meet to be eligible for TennCare. As an elder law attorney, one of my jobs is to help families get their loved ones qualified for TennCare while maintaining resources available for the rest of the household.
One of the ways that we do this is by restructuring a family’s assets. We do this by turning resources that are countable for TennCare purposes into items that TennCare does not count as part of its eligibility assessment
This process is known in the elder law community as a spend-down. The goal of the spend-down is to make you or your loved one eligible for TennCare as far as your assets are concerned. If you are overqualified for income-based criteria, we can use a special type of trust called a Qualified Income Trust, or a Miller Trust, to reduce your income. The goal of a spend-down is to maintain the quality of life for all family members including those who need long-term care.
Bob might benefit from purchasing a quality mobility device
What is a “spend-down”?
For example…
Bob needs to go into long-term care. Bob is eligible based on his income. He makes $2,000.00 a month of social security retirement income. Bob also has a house, a car, and $50,000.00 in the bank. Bob is widowed and his children are adults.
We need to do something with at least $48,000.00 from Bob’s bank account in order to make him eligible for TennCare. His house and his car are not countable for TennCare purposes in most cases. What can we do?
Make improvements to his home that would improve his quality of life and access to the things that he needed in the home. This might include:
Grab bars in the shower or hallway.
A ramp into the main entrances.
Paving the driveway or expanding it closer to the door
Widening doors
Buy some things for Bob that his Medicare did not cover, such as:
Hearing aids
Dentures
Eyeglasses
Top of the line mobility devices
There may be other things that would improve Bob’s quality of life. There are things we can spend money on or convert into income. I am also going to suggest to everyone that they use the money to make arrangements for end-of-life needs if they have not done so already. Since at some point Bob’s children will need to make arrangements for his burial or cremation, paying for it now from his excess funds is a great way to make those funds unavailable for TennCare purposes and meet a future need.
Bob has peace of mind because he has plans in place for long-term care
Bob might want a Care and Savings Assessment
It’s not easy getting approved for TennCare / Medicaid, and we know it! That’s why we offer help in planning your steps to qualify. It doesn’t matter what your starting point is, we’re here to help you navigate the process with one goal: get our clients the quality of care that they need. Contact us if you would like to make plans for qualifying for TennCare.
Quite simply, TennCare is Tennessee’s Medicaid program. While the name “TennCare” has the word “care” in it, it is NOT Medicare. In order to further clarify the difference between the terms “Medicaid” and “Medicare,” you need to remember that we use “Medicare” to “care” for our elders and “Medicaid” to “aid” those, of any age, in need. Essentially TennCare is Tennessee’s brand of Medicaid. Hopefully, that little trick will help you remember the differences between each program.
Who qualifies for TennCare?
Now that you are familiar with the difference between Medicare and Medicaid, let’s discuss who qualifies for TennCare (Medicaid).
There are three qualification criteria that you must meet in order to obtain Medicaid/TennCare.
1. Medical qualification –There is a special medical test that applicants must pass in order to qualify. Usually, a care facility will handle this piece of the Medicaid application.
2. Asset qualification – A TennCare applicant who is single can only have $2,000.00 in assets before they are eligible for TennCare. Vehicles and real estate are usually exempt from the count of assets. A “Care and Savings Assessment” is a good place to start if the applicant needs help with figuring out what they have in assets and what options are available to make excess assets “non-countable” for TennCare purposes.
3. Income qualification – A TennCare applicant can only receive $2,382.00 per month (as of 2021) in order to receive TennCare. If an applicant has more than this amount in income, an attorney can resolve it through what is called a Miller Trust or a Qualified Income Trust.
Long-term care is very expensive
Why should I be concerned about long-term care services?
Unless you are a millionaire or multi-millionaire, TennCare eligibility and designation could have a major impact on your finances and your family. While you may not need TennCare now, you will want to plan as if you will need it in the future. As you may have heard us say before “we hope for the best, and plan for the worst.” Having a plan is an effective way to ensure that you will have long-term care coverage when you need it. This isn’t to say that you won’t find yourself needing TennCare much sooner than expected. When this happens we call it “TennCare Crisis Planning”.
Knowing your options makes all the difference
I don’t know where to start!
The biggest obstacle to TennCare planning is determining what to do with your assets and income; especially if there is excess in any category. There are a lot of rules and potential pitfalls that you need to look out for. Fortunately, we have some great financial planning and legal resources that can help our clients. If you have an immediate need for TennCare or want to plan for TennCare we can supply the client with what we call a “Care and Savings Assessment”. It’s a wonderful tool that helps people effectively navigate through their options.
How do we help our estate planning clients with TennCare planning?
For our estate planning clients, we like to take into consideration the possibility that you may need TennCare in the future.
For example, it is our priority to set up our client estate plans to make sure that TennCare is accessible if it is ever needed. As with many government organizations, Medicaid has lots of rules to follow and many people find that they did not know what rules they were supposed to be following until it was too late! Fortunately for our clients, we know the rules and can help you plan in advance of ever needing to apply for TennCare to cover medical care. Additionally, we create documents that make sure that someone can apply for Tenncare on your behalf. This is useful if you become incapacitated in the future.
How do we help our Conservatorship clients with TennCare?
Many of our conservatorship clients are caregivers for a loved one who requires skilled nursing to keep them safe. The average cost for this type of care is about $7,000.00 per month or more. There is usually a large gap between monthly income and fees. Our firm can navigate the TennCare application process and assure that the appropriate language is in the conservatorship order paperwork with the court so that the client may obtain the appropriate benefits for their loved one.
How do we help clients with TennCare Crisis planning?
For those who have never considered the cost of long-term care until they or a loved one need to enter a nursing facility, the cost of care is likely to come as a shock- and an unaffordable, but necessary, expense. This is when we can step in with what we call “crisis planning,” meaning that you need a plan and you need a plan now.
In these cases, we are able to look at the household financial situation of the person needing skilled care, as well as the family situation overall, and come up with a plan for how to best use existing resources and get them qualified for TennCare benefits to pay for the nursing home bills. This process called our “Care and Savings Assessment”, is one of the most rewarding things that we do! It allows us to help people get the care that they need while still providing a quality of life for themselves and their families.
If you are concerned about accessing TennCare benefits for long-term care, contact our office for a complimentary initial call using our online calendar here.
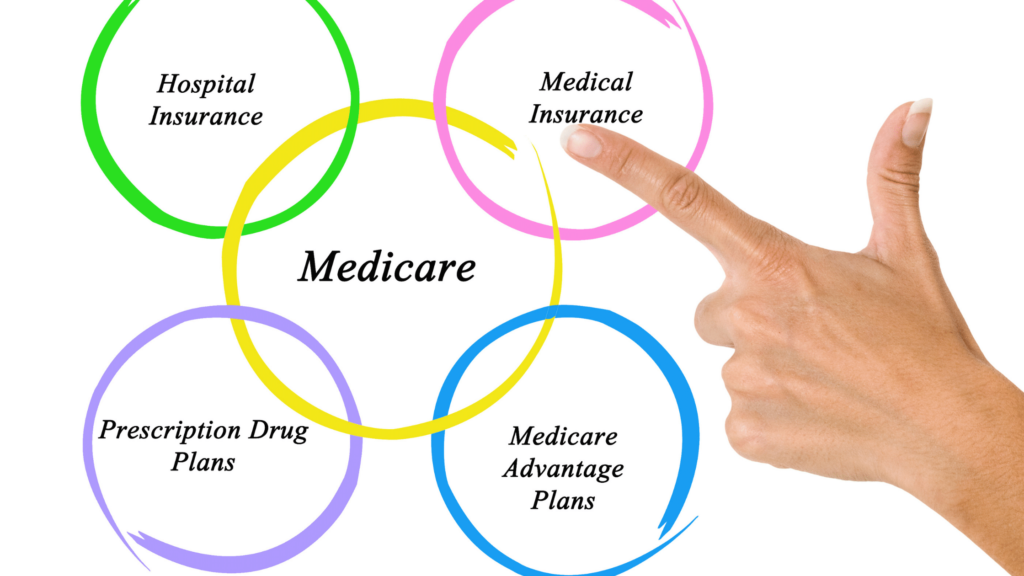
As if choosing health insurance under an employer’s plan wasn’t difficult enough, figuring out which type of Medicare plan is best for you is even more confusing. I call Medicare an alphabet because there are 4 parts- A, B, C, and D. Oh, and you might want to consider a supplement too!
Don’t worry. With a little time and some guidance, you can master the Medicare alphabet just like you mastered your ABCs!
First, let’s go through the four types and what they cover.
Part A only covers emergency care, such as if you need to stay at the hospital.
Part B covers regular care like doctors visits, bloodwork, and any other testing or treatment that your doctor recommends.
Part C is often referred to as an “Advantage Plan”. It is administered by private insurance companies, just like an employer’s plan. It includes Part A and B coverage and may include other benefits as well, such as dental, vision, and prescription drugs.
Part D covers prescription drugs. That’s it.
When you approach age 65, ask yourself what your current health needs are, what family history might impact future healthcare needs, and what type of coverage you are used to receiving. Then look at your budget.
Part A is free for those who are eligible through their tax contributions. In 2021, most individuals will pay $148.50 per month for Part B, although the amount can be higher depending on your income.
If you anticipate that you will need something more than just emergency and regular doctor’s visits, there is another alternative. Consider a Part C “Advantage” plan or a Medicare Supplement (or “Medigap” plan), instead. This plan will provide coverage for those things that Parts A and B don’t, like such as prescription medications, dental, or vision care. Keep in mind that you still pay co-pays and deductibles on Medicare, so you will want to look at those amounts and not just your premium when considering your budget.
When thinking about the Medicare alphabet, I have a little way to help me remember what each part covers:
A is for an Accident that lands you in the hospital
B is for Bloodwork they do at the doctor’s office
C is for Comprehensive coverage you can get with an Advantage plan
D is for Drugs (They made that one easy!)
Now you know your ABCs….next week I hope you’ll join us when I share my favorite FREE resources to learn about Medicare before you sign up.
Choosing a legal guardian who can raise your kids if you are unexpectedly incapacitated or pass away can be a daunting and difficult challenge. There are many things to take into account such as parenting styles and the potential guardian’s ability to love and take care of your children.
These are just some of the questions we believe every parent should answer before naming a guardian.
Where will your children live? Many parents desire to keep their children in a familiar environment if something unfortunate happens. It’s not unusual for parents to put instructions in their estate plans regarding the cities or states they want their kids to be raised in if mom or dad passes away. If the geographical location of where your kids will be placed is important to you, be sure to make this known to your Davidson County will attorney when creating your plan.
Are your children familiar with the potential guardian? It is important that your children are comfortable with the guardian you are about to choose for them. If you are selecting a guardian that lives far away, you may want to consider ways to begin cultivating a relationship between your children and the potential guardian before it’s needed. Naming a temporary guardian is also important in such situations. This will ideally be a person that lives close by and can help ease the transition to your kids relocating to their permanent guardian’s home.
Is your potential guardian prepared to care for your children? There are many factors that could fall under this category, but it is important to make sure that your guardian is emotionally, physically, and financially prepared to care for your child/ren. For example, you may want a grandparent to become guardian, but their age and their own financial and/or medical needs may make serving in this role difficult for them. Don’t forget to take their point of view into account when making your selection.
Do any of your children need special care? If you have a child with a mental or physical disability, it could take special knowledge and resources to care for your child. It is important to make sure that the named guardian would not be overwhelmed by this responsibility and that they are prepared to care for your child in whatever way that your child may need.
Have you discussed this choice with your potential guardian? It is very important that you ask your potential guardian if this is a responsibility that they can take on. You will also want to talk about your desired path for raising your child/ren to make sure that you are in agreement and that your wishes will be followed.
As parents, you spend a lot of time planning the best future for your children. Make sure that your planning includes naming a legal guardian should you become unexpectedly incapacitated or pass away. You should be the one making that decision – not the courts. Schedule a call with our Davidson County will law firm today, so you can have the peace of mind knowing your children will be cared for by the person you want, in the way you want if anything happens to you.